We do not assume you will switch. Bring your policy document and we will check together what you are covered for, until when and how much. Decide whether to review afterwards.
Stories
Does this sound familiar?
Three short comics about common insurance situations.
01
The policy I signed up for without thinking
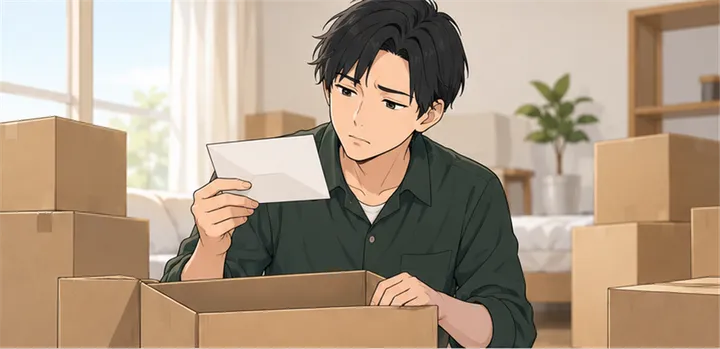
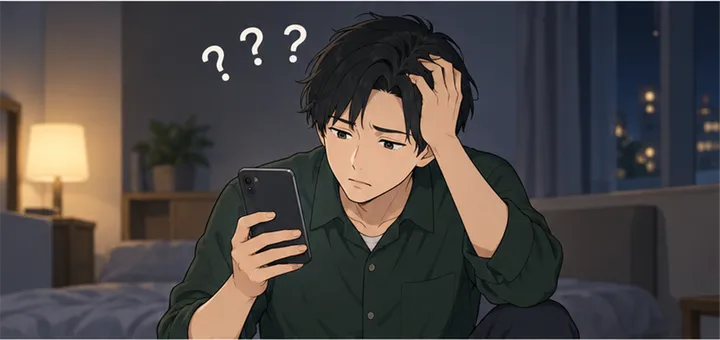
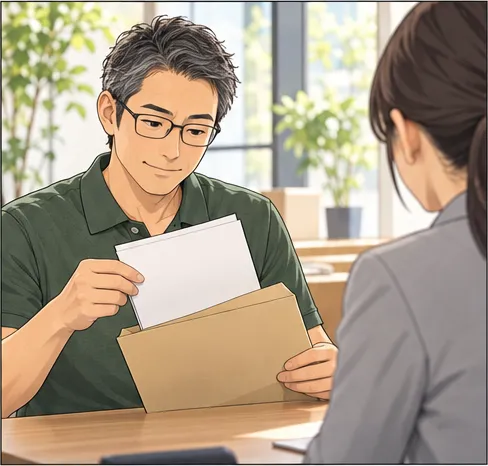
An envelope that turned up while unpacking after a move.
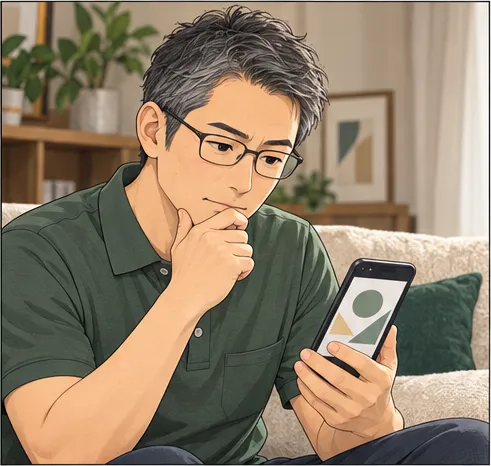
Huh… what insurance is this again?
When I joined the company, they said everyone had it, so I just signed…
The terms are hard to follow, and it feels too late to ask…
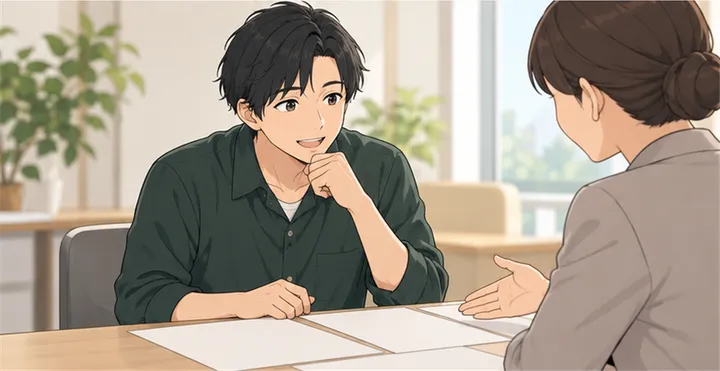
AdvisorLet's start by checking together what you are covered for.
I'm glad I asked.
These comics are fiction and unrelated to real people or contracts. Outcomes vary with age, health, contract terms and other factors.
We check what the main contract and any riders each cover.
02
Until when you are covered
We check the coverage period and whether it renews (and whether premiums change at renewal).
03
How much you are covered for
We check the amount paid out in an emergency and benefits for hospitalisation and similar events.
04
Overlap with other cover
We check for overlap with public cover, employer schemes and mortgage life cover.
Before you switch
What to know before reviewing
Cancelling your current insurance and taking out a new policy can leave you worse off.
Premiums for a new policy are often higher as you get older.
Depending on your health, you may not be able to take out a new policy, or conditions may apply.
The surrender value you receive on cancelling is often less than the total premiums paid.
Cancelling may mean losing riders, dividends and other rights.
Some new policies have a waiting period before cover starts or a period when benefits are not paid.
After cancelling, you may not be able to return to the original contract. When switching, confirm that the new contract is in force and when each type of cover starts (including any waiting period), and cancel only when there will be no gap in cover.
You can also review while keeping your current contract
You can keep the main contract and add or remove riders or reduce the amount of cover. Cover that is removed or reduced will be lost, so we check the details with you first.
Flow
How a policy check works
01
Booking
Let us know a convenient date and time by phone or through the contact form.
02
Checking your policy together
We explain in plain words what you are covered for, until when and how much.
03
Deciding together whether to keep or review
If keeping your policy is better, we will tell you so.
04
The decision is yours
We will not ask you to sign up on the spot. Take it home and think it over with your family.
What to bring
Your policy document (or the annual contract statement)
Mortgage documents, if you have them (showing the mortgage life cover)
Documents on your employer's schemes, if you have them
You can consult us even without them.
FAQ
Frequently asked questions
Q
I can't find my policy document.
A
You can also check the annual contract statement from your insurer or the insurer's policyholder page. If you are unsure, please consult us first.
Q
Can you check insurance I took out elsewhere?
A
Yes. We will check it with you wherever you took it out.
Q
Will you push me to switch?
A
If keeping your policy is better, we will tell you so. When reviewing, we start with ways to adjust riders and similar options while keeping your current contract.
Q
Can you look at my family's insurance too?
A
Yes. We can also check for overlap in your family's cover.
* Cover and premiums differ by insurer, product, age and other factors. See our insurance solicitation policy for the insurers we represent.View our insurance solicitation policy
Contact
Shall we check your current insurance together?
Start with a 30-minute call. Having your policy at hand makes checking faster.